

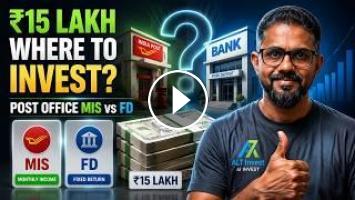
Post Office MIS vs Fixed Deposit — which is better for investing ₹15 lakh safely?
This video explains the right choice based on income needs, growth goals, and flexibility.
If you have received a lump sum amount from retirement benefits, property sale, PF, gratuity, or savings, choosing between Post Office Monthly Income Scheme (MIS) and Fixed Deposit can be confusing.
The highest interest rate is not always the best option — the right investment depends on what you need your money to do.
In this detailed comparison, we compare three options: Post Office MIS, Non-Cumulative Fixed Deposit, and Cumulative Fixed Deposit.
You will understand how monthly income, compounding, liquidity, taxation, TDS rules, and inflation impact your final decision.
Using an example of ₹15 lakh, we explain how Post Office MIS can generate approximately ₹9,250 monthly income, how a non-cumulative FD works for regular interest payouts, and how a cumulative FD focuses on wealth creation through compounding.
Which is better — Post Office MIS or FD? The answer depends on your financial goal. If you need predictable monthly income, MIS may suit your requirement.
If you don't need income and want your money to compound, a cumulative FD may be more suitable. If flexibility is important, FD options and withdrawal rules need careful comparison.
This video also covers premature withdrawal rules, taxation of interest income, the TDS difference between MIS and FD, inflation impact on fixed income investments, and how investors can think about balancing safety, income, and long-term growth.
Chapters
00:00 Introduction: Post Office MIS vs Fixed Deposit Explained
02:10 Who Should Choose MIS or FD? Understanding Investor Goals
04:15 Three Options Explained: MIS, Non-Cumulative FD & Cumulative FD
06:30 ₹15 Lakh Comparison: Post Office MIS vs FD Numbers
09:30 Which Option Gives Monthly Income vs Wealth Growth?
11:00 Premature Withdrawal Rules: MIS vs Fixed Deposit Liquidity
12:30 Taxation & TDS Difference Between MIS and FD
14:00 Inflation Impact on Fixed Income Investments
15:15 Can You Make MIS Income Work Harder?
16:30 Which One Would I Choose? Final Decision Framework
18:00 Final Takeaway: Choosing the Right Investment Goal
If this video helped you understand Post Office MIS vs FD, share it with someone planning retirement or investing a lump sum. Subscribe to ALT Invest for practical investing and personal finance videos every week.
#PostOfficeMIS
#fixeddepositinterestrates
#PersonalFinance
#ALTInvest
#postofficeschemes
#postofficesavings
#postofficeinterestrates
#bestfd
#fixeddeposits
#FD
post office mis vs fd, post office monthly income scheme, post office mis 2026, fixed deposit vs post office mis, fd vs mis which is better, best investment for 15 lakh, 15 lakh investment options, monthly income scheme post office, post office investment schemes, fixed deposit interest rates, cumulative fd vs non cumulative fd, fd monthly income, safe investment options india, retirement planning india, senior citizen investment options, guaranteed income investment, passive income india,
- Категория
- Схемы по заработку в интернете
Комментариев нет.
Следующее
Auto
-
00:07

Post Office Schemes New Interest Rates From 1 Jul 26 - 30 Sep 26 #post #investing
-
00:54
How ₹2.5 Lakh Can Help You Build A ₹5 Lakh/Month Meesho Business | Ecommerce Business Strategy
-
05:53
Post Office MIS Scheme 2026, Best Investment Plan for Monthly Income, MIS Scheme 2026 Interest Rate
-
00:07
Post Office Monthly Income Scheme 2026 l Post Office MIS 2 Lacs monthly income calculation #money
-
05:22
Post Office MIS Scheme 2026, Best Investment Plan for Monthly Income, MIS Scheme 2026 Interest Rate
-
05:08
Post Office MIS Scheme 2026, Best Investment Plan for Monthly Income, MIS Scheme 2026 Interest Rate
-
00:07
Senior Citizen Saving Scheme 16 Lacs Investment Amount Calculation #money #investing
-
00:07
Post Office FD 2026 l post office fd complete details, rules & calculation #money #investing
-
13:31
RESP Deposit and Investment Strategy (2026)
-
00:06
Senior Citizen Savings Scheme 1 Lacs Investment Amount Calculation #money #investing
-
05:33

ЗАРАБОТОК В ИНТЕРНЕТЕ | КРУТАЯ СХЕМА | FUNPAY
-
08:12

Пассивный Заработок 1000Р в День в Интернете на Телефоне Без Вложений
-
06:43
Как ЗАРАБОТАТЬ ШКОЛЬНИКУ в ИНТЕРНЕТЕ? Самые Легкие Способы Заработка
-
07:05

ЗАРАБОТОК В ИНТЕРНЕТЕ 2023 | Реальный заработок в интернете с вложением | Как заработать в интернете
-
05:49

ЗАРАБОТОК В ИНТЕРНЕТЕ 2023 | Реальный Заработок В Интернете С Вложением. Как Заработать В Интернете?
-
04:28

Схема заработка 2023 ! Зарабатываем в интернете онлайн сидя дома ! Заработок денег ! Деньги легко !
-
05:33

ЗАРАБОТОК В ИНТЕРНЕТЕ | КРУТАЯ СХЕМА | FUNPAY
-
06:43

Как ЗАРАБОТАТЬ ШКОЛЬНИКУ в ИНТЕРНЕТЕ? Самые Легкие Способы Заработка
-
14:53

Показываю Как Зарабатывать Деньги - Заработок В Интернете 2023 Рабочая Схема Для Заработка
-
14:12

Большой Заработок В Интернете С Выводом Рабочая Схема Заработка
 Загрузка...